GGMA Morning Briefing: AI rally takes a breather
The AI rally took its first real breather. Asian equities pared early losses to hold near records as investors bought the dip following a pullback in the artificial-intelligence trade, with stalled US-Iran peace efforts giving traders an excuse to lock in profits near record highs. Crude pared the prior session’s advance as Israel and Iran stepped back from fresh threats, easing the inflation impulse and letting Treasuries firm (Nytimes).
Chinese tech led the regional bid, with Hong Kong and mainland gauges firming (BBG) (BBG). The Chinese yuan climbed to its strongest level against a trade-weighted basket since 2022. The move reflects firmer flows and Beijing’s tolerance for some appreciation. It comes alongside a deepening domestic bond rally. (BBG) Regarding the latter, the People’s Bank of China trimmed its open-market cash operation to a record low as the domestic bond rally extended. The step reflects comfortable liquidity conditions. Falling Chinese yields underline the soft-growth, easy-policy backdrop. (BBG)
In FX, the US Dollar was only a little changed. The yen held its weak levels after Finance Minister Katayama said authorities stand ready to act in the currency market as needed (BBG). Meanwhile, Sumitomo Mitsui Financial Group’s global markets chief said the Bank of Japan should lay out a clear path for policy normalisation after a widely expected rate hike this month to stabilise the bond market. (Channelnewsasia).
Cheaper oil lifted Treasury futures, with Pimco arguing Fed-policy bets — not AI-related issuance — are driving yields for now (BBG). JGB’s rallied overnight across the curve. This comes despite Japan weighing a consumption-tax cut to take effect in April 2027, according to a Mainichi report.
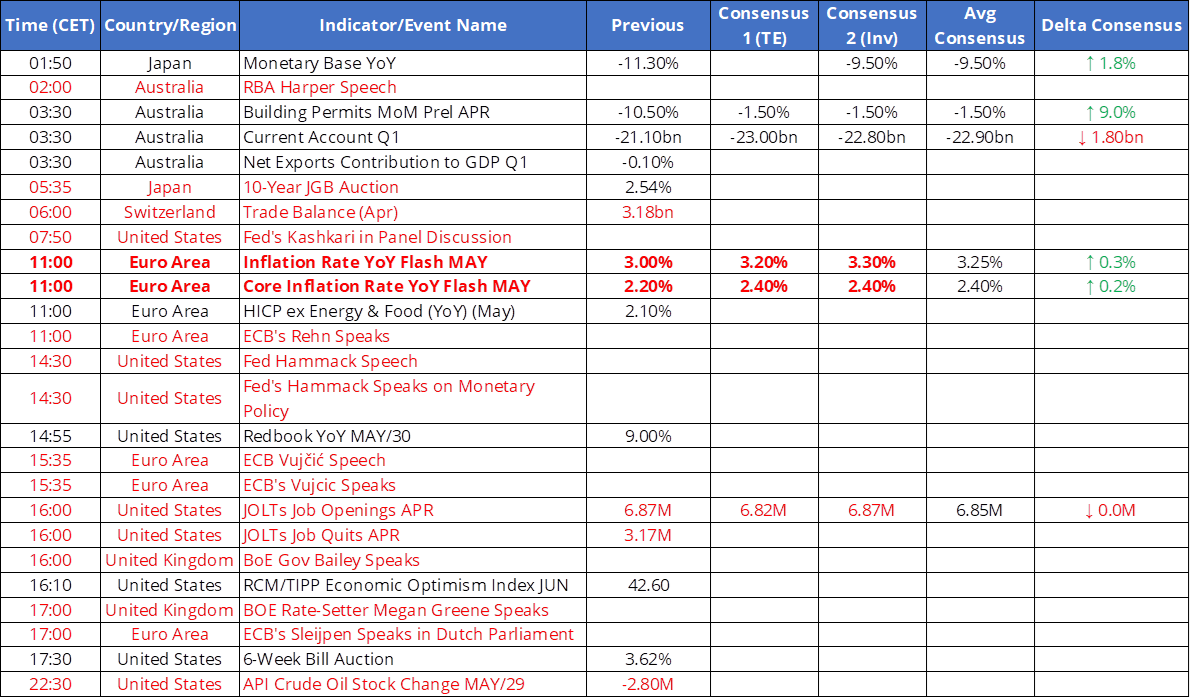
On the data front, Australia’s first-quarter GDP partials came in soft across the board — a wider-than-expected current-account deficit, a bigger net-export drag, and a contraction in company operating profits — pointing to a weak Q1 GDP print on Wednesday.
Japan’s monetary base contracted further as the BoJ runs down its balance sheet, while a Bloomberg Opinion piece argued incoming Fed chair Kevin Warsh’s plan to reshape the central bank could get messy quickly (BBG).
On the policy maker front, RBA board member Ian Harper flagged concern over an uptick in inflation expectations in his first individual board-member speech, and a firm national minimum-wage rise kept wage pressure alive (BBG) (BBG).
The AI-capex arms race dominated the corporate tape: Alphabet unveiled a large equity raise, including a Berkshire Hathaway deal, Anthropic filed confidentially for an IPO ahead of OpenAI, and Hewlett Packard Enterprise jumped on a strong AI-server outlook (BBG) (BBG); Nvidia’s Jensen Huang reassured on supply capacity (Reuters). A rare caution came from Australia’s CBA, which flagged surging AI running costs (USNews).
Today’s Macro Roadmap: RBA, ECB, BOE & Fed speak / EZ inflation / US JOLTS
On the policy maker front, the Fed’s Kashkari will speak at 07:50 CET. In his last speech, he said it’s too early to conclude that interest rates need to rise, while arguing that the central bank should keep all options on the table. “I think it’s premature for me to conclude we need to be raising rates right away,” Kashkari said Friday at an event at Korea University in Seoul. “We need to keep watching the data and watching how the conflict in the Middle East unfolds before I want to make any adjustments.” (BBG)
The ECB’s Olli Rehn will speak at 11:00 CET. On May 21st, he said that the European Central Bank may have to tighten monetary policy to protect its credibility after the Iran war sent inflation past the 2% target. He said that the euro zone is sliding toward the ECB’s adverse scenario of slower economic expansion and faster inflation, which may force it to raise interest rates “for the sake of credibility.” He added that, for now, “we see some vibration in the short-term inflation expectations, but no significant deviation in medium- to long-term inflation expectations.”
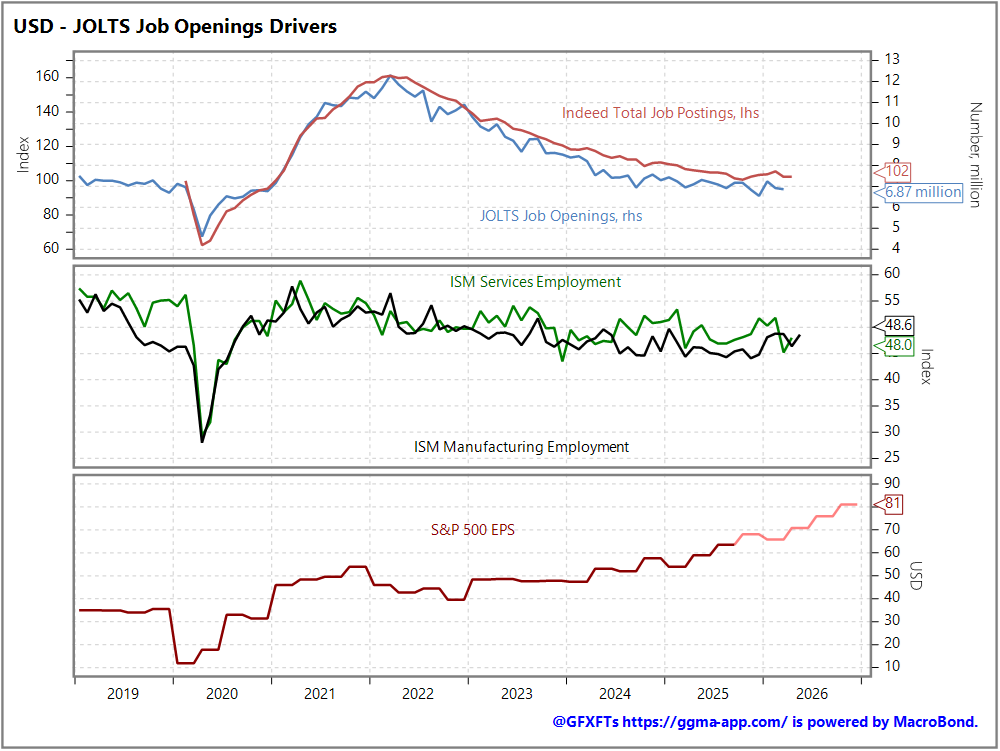
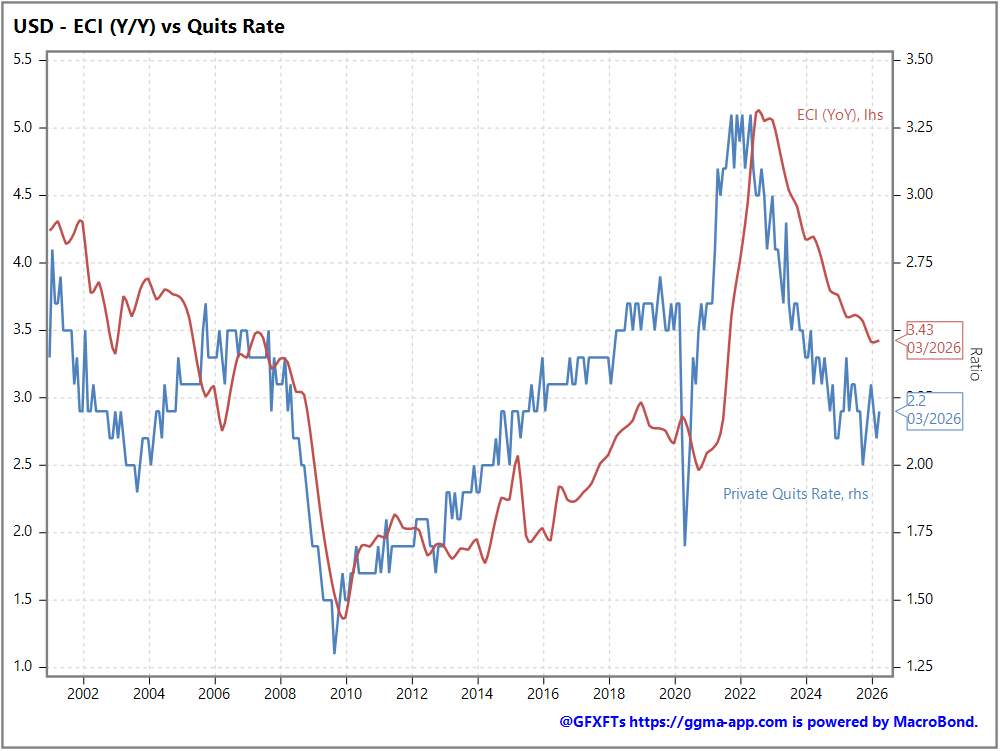
In the US, the JOLTS report for April could attract attention, especially the quits rate, which correlates well with wages. Analysts note that the rate of decline in openings is gradually slowing; Indeed daily postings are stabilising and layoffs (claims/Challenger/WARN) remain contained.
Good luck, and feel free to ping me in the chat to discuss markets and views!
PS:
· Did you know that you can register and follow us 24/7 here? Then download our app from the Apple Store to listen to our Squawk on the go or chat with us live.
If you are on Bloomberg and would like to see my comments in real-time, or if you are a MacroBond user and would like to get access to my chart bank, please send an email to: [email protected] .
Financial Markets Monitor
·
Disclaimer: This article is for informational and educational purposes only and should not be construed as financial, investment, or professional advice. The content represents the author's personal views and analysis and does not constitute a recommendation to buy, sell, or hold any securities or financial instruments. Readers should conduct their own research and consult with a qualified financial advisor before making any investment decisions. Past performance is not indicative of future results, and all investments carry risk, including the potential loss of principal.
The AI rally took its first real breather. Asian equities pared early losses to hold near records as investors bought the dip following a pullback in the artificial-intelligence trade, with stalled US-Iran peace efforts giving traders an excuse to lock in profits near record highs. Crude pared the prior session’s advance as Israel and Iran stepped back from fresh threats, easing the inflation impulse and letting Treasuries firm (Nytimes).
Chinese tech led the regional bid, with Hong Kong and mainland gauges firming (BBG) (BBG). The Chinese yuan climbed to its strongest level against a trade-weighted basket since 2022. The move reflects firmer flows and Beijing’s tolerance for some appreciation. It comes alongside a deepening domestic bond rally. (BBG) Regarding the latter, the People’s Bank of China trimmed its open-market cash operation to a record low as the domestic bond rally extended. The step reflects comfortable liquidity conditions. Falling Chinese yields underline the soft-growth, easy-policy backdrop. (BBG)
In FX, the US Dollar was only a little changed. The yen held its weak levels after Finance Minister Katayama said authorities stand ready to act in the currency market as needed (BBG). Meanwhile, Sumitomo Mitsui Financial Group’s global markets chief said the Bank of Japan should lay out a clear path for policy normalisation after a widely expected rate hike this month to stabilise the bond market. (Channelnewsasia).
Cheaper oil lifted Treasury futures, with Pimco arguing Fed-policy bets — not AI-related issuance — are driving yields for now (BBG). JGB’s rallied overnight across the curve. This comes despite Japan weighing a consumption-tax cut to take effect in April 2027, according to a Mainichi report.
On the data front, Australia’s first-quarter GDP partials came in soft across the board — a wider-than-expected current-account deficit, a bigger net-export drag, and a contraction in company operating profits — pointing to a weak Q1 GDP print on Wednesday.
Japan’s monetary base contracted further as the BoJ runs down its balance sheet, while a Bloomberg Opinion piece argued incoming Fed chair Kevin Warsh’s plan to reshape the central bank could get messy quickly (BBG).
On the policy maker front, RBA board member Ian Harper flagged concern over an uptick in inflation expectations in his first individual board-member speech, and a firm national minimum-wage rise kept wage pressure alive (BBG) (BBG).
The AI-capex arms race dominated the corporate tape: Alphabet unveiled a large equity raise, including a Berkshire Hathaway deal, Anthropic filed confidentially for an IPO ahead of OpenAI, and Hewlett Packard Enterprise jumped on a strong AI-server outlook (BBG) (BBG); Nvidia’s Jensen Huang reassured on supply capacity (Reuters). A rare caution came from Australia’s CBA, which flagged surging AI running costs (USNews).
Today’s Macro Roadmap: RBA, ECB, BOE & Fed speak / EZ inflation / US JOLTS
On the policy maker front, the Fed’s Kashkari will speak at 07:50 CET. In his last speech, he said it’s too early to conclude that interest rates need to rise, while arguing that the central bank should keep all options on the table. “I think it’s premature for me to conclude we need to be raising rates right away,” Kashkari said Friday at an event at Korea University in Seoul. “We need to keep watching the data and watching how the conflict in the Middle East unfolds before I want to make any adjustments.” (BBG)
The ECB’s Olli Rehn will speak at 11:00 CET. On May 21st, he said that the European Central Bank may have to tighten monetary policy to protect its credibility after the Iran war sent inflation past the 2% target. He said that the euro zone is sliding toward the ECB’s adverse scenario of slower economic expansion and faster inflation, which may force it to raise interest rates “for the sake of credibility.” He added that, for now, “we see some vibration in the short-term inflation expectations, but no significant deviation in medium- to long-term inflation expectations.”
In the US, the JOLTS report for April could attract attention, especially the quits rate, which correlates well with wages. Analysts note that the rate of decline in openings is gradually slowing; Indeed daily postings are stabilising and layoffs (claims/Challenger/WARN) remain contained.
Good luck, and feel free to ping me in the chat to discuss markets and views!
PS:
· Did you know that you can register and follow us 24/7 here? Then download our app from the Apple Store to listen to our Squawk on the go or chat with us live.
If you are on Bloomberg and would like to see my comments in real-time, or if you are a MacroBond user and would like to get access to my chart bank, please send an email to: [email protected] .
Financial Markets Monitor
·
Disclaimer: This article is for informational and educational purposes only and should not be construed as financial, investment, or professional advice. The content represents the author's personal views and analysis and does not constitute a recommendation to buy, sell, or hold any securities or financial instruments. Readers should conduct their own research and consult with a qualified financial advisor before making any investment decisions. Past performance is not indicative of future results, and all investments carry risk, including the potential loss of principal.