GGMA Morning Brief: Stocks’ AI-fuelled rally continues / Today: BOC & Fed speak / Swiss sight deposits / US ISM mfg.
Global equities pushed to fresh records at the start of the week and the new month, as relentless enthusiasm for the artificial-intelligence trade overpowered an elevated Middle East risk backdrop (BBG). Tech-heavy benchmarks in South Korea, Taiwan and Japan led the charge, with the semiconductor rally now the dominant force in global markets and openly fuelling a debate over how much further it can run (BBG). Offsetting the upbeat tone, oil’s rebound after its steepest monthly drop in more than six years revived energy-inflation concerns that could complicate the recent recovery in bond markets (BBG).
The US dollar was only a little changed. Regarding the Australian dollar, analysts see scope for it to lose more ground against the New Zealand dollar, driven by diverging rate expectations between the RBA and the RBNZ. The call reflects shifting relative-policy bets across the Antipodean pair. It comes alongside soft Australian housing and inflation-gauge data. (BBG)
Japan’s Nikkei climbed to a record as SoftBank surged toward becoming the country’s most valuable company (USNews), while South Korean export growth hit a four-decade high on the AI-chip boom (Reuters). The yen stayed weak despite record official intervention, as investors wait for a Bank of Japan rate hike, keeping the currency in what Tokyo officials call a danger zone (BBG) (Reuters).
Bond futures in Germany and Japan eased as global yields climbed on the inflation impulse, and bond-market volatility firmed ahead of this week’s US jobs report (BBG). Central banks also struck a hawkish chord: the ECB’s Isabel Schnabel warned the war’s energy shock risks unanchoring inflation expectations (BBG), a growing number of Fed officials are openly weighing a possible rate hike (Reuters), and the BoE’s Catherine Mann said the “good luck” of the low-inflation era has run out (GoogleNews). Fed Chair Jerome Powell defended central bank independence, warning that credibility would be lost if a president could fire officials (BBG), even as the Wall Street Journal reported that incoming chair Kevin Warsh wants to rethink the policy framework (WSJ). The Fed’s Kashkari said that he is waiting for more data before changing course.
On the data front, Japan’s first-quarter corporate profits beat sharply even as capital spending stalled on a war-clouded outlook (BBG), while China’s private factory gauge slowed but held in expansion against a weaker official reading (BBG) (BBG).
On the crypto front, Bank of England policymaker Megan Greene said demand for stablecoins may soon fade, pushing back on expectations of rapid mainstream adoption. The view contrasts with US officials’ more constructive framing. Federal Reserve Governor Christopher Waller said the spread of stablecoins around the world could amplify the influence of US central-bank policy. (BBG)
In the corporate tape, Nvidia’s move into the Windows laptop market lifted tech sentiment further, taking the AI leader head-to-head with Intel and AMD (Axios), while Berkshire Hathaway agreed to buy homebuilder Taylor Morrison in the first major deal under chief executive Greg Abel (BBG). Copper firmed as a US tariffs deadline less than a month away pulled demand forward (BBG). With US-Iran negotiations still unresolved (SCMP) and this week’s US payrolls looming as a gut-check for rate-hike bets (BBG), the tug-of-war between AI optimism and geopolitical risk sets the tone into June.
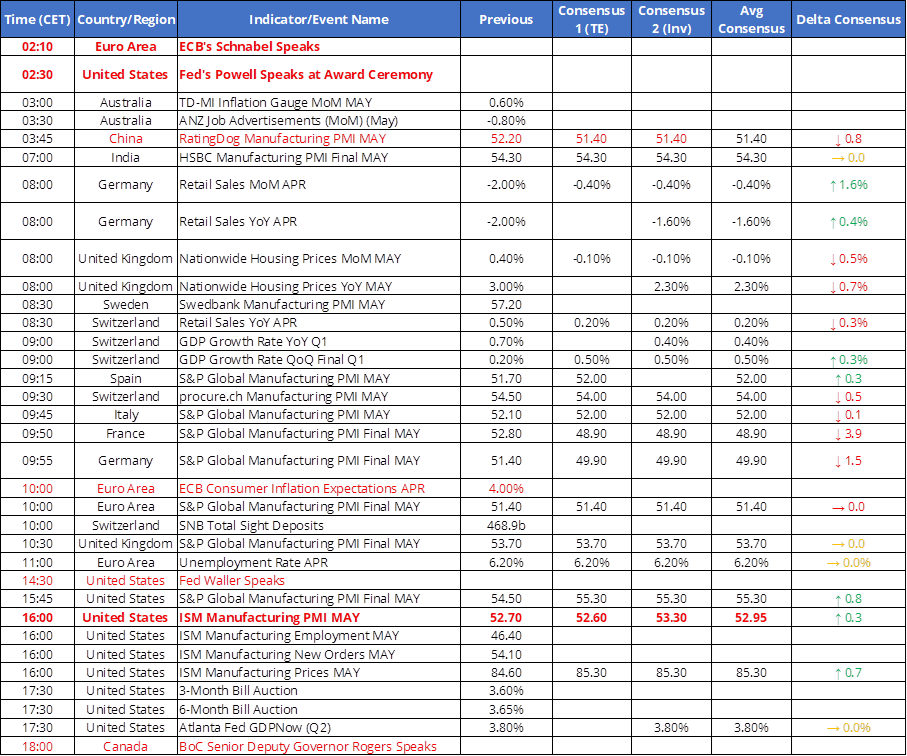
Today’s Macro Roadmap: BOC & Fed speak / Swiss sight deposits / US ISM mfg.
Fed’s Waller will speak today at 14:30 CET. He has recently moved from the dovish to the more hawkish camp. On 29 May, he said he would support a rate hike if inflation expectations become unanchored, citing the rise in medium-term expectations since the energy shock — hardening his 22 May Frankfurt lecture, where he’d already said the next move is ‘just as likely to be a hike as a cut.’ This is a full reversal of his early-2026 stance (he dissented at the January FOMC for a 25bp cut, judging inflation near-target and labour risks dominant).
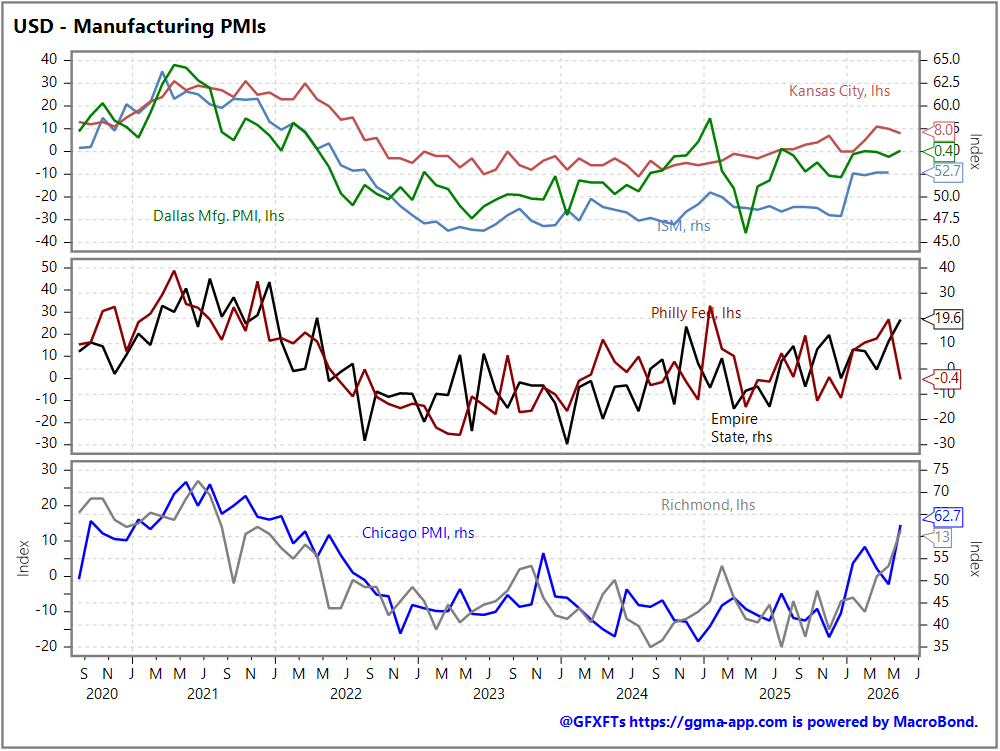
On the data front, the US ISM manufacturing survey for May will be the key release today. The consensus expects a slight improvement in the headline number. Also important to watch will be the prices-paid component, which is expected to increase.
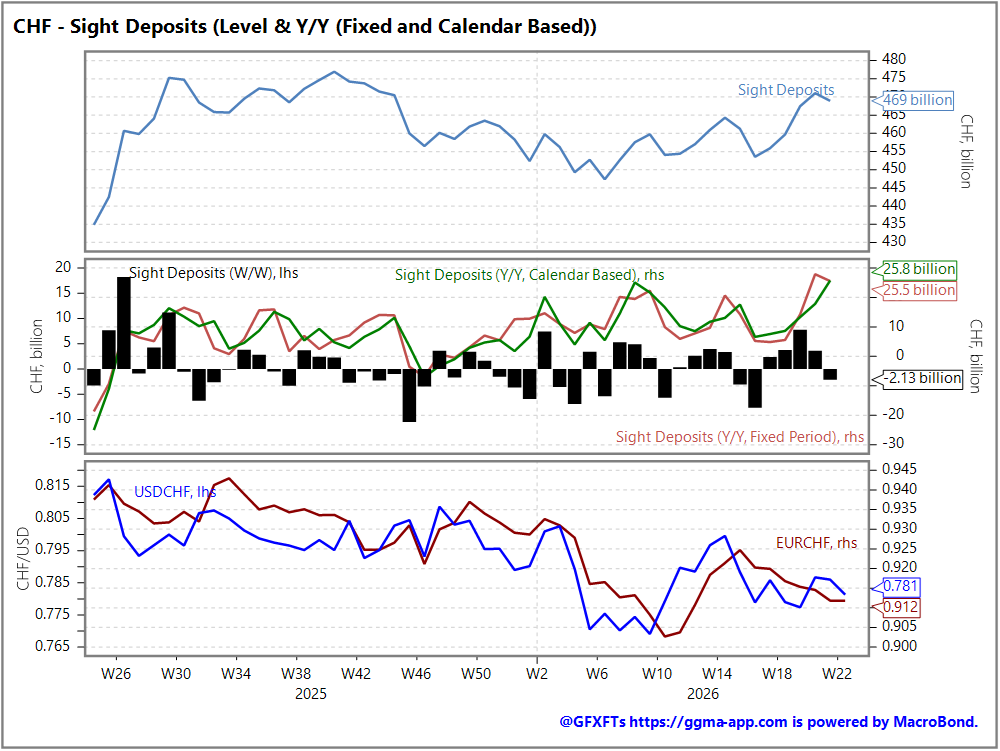
In Switzerland, the SNB will release its update on sight deposits for last week at 10:00 CET. They are far from a perfect proxy for SNB interventions in foreign exchange markets and are influenced by other factors, yet they remain worth monitoring. In its latest statement, the central bank said that
“in view of international developments, we are increasingly prepared to intervene in the foreign exchange market. We stand ready to intervene in the foreign exchange market to curb a rapid and excessive appreciation of the Swiss franc, which would jeopardise price stability.”
Good luck, and feel free to ping me in the chat to discuss markets and views!
PS:
· Did you know that you can register and follow us 24/7 here? Then download our app from the Apple Store to listen to our Squawk on the go or chat with us live.
If you are on Bloomberg and would like to see my comments in real-time, or if you are a MacroBond user and would like to get access to my chart bank, please send an email to: [email protected] .
Financial Markets Monitor
·
Disclaimer: This article is for informational and educational purposes only and should not be construed as financial, investment, or professional advice. The content represents the author's personal views and analysis and does not constitute a recommendation to buy, sell, or hold any securities or financial instruments. Readers should conduct their own research and consult with a qualified financial advisor before making any investment decisions. Past performance is not indicative of future results, and all investments carry risk, including the potential loss of principal.